If you have been reading about payment processors, the names and terms can pile up quickly, so it helps to see how the pieces fit together. The top major payment processors range from merchant acquirers to all-in-one apps and enterprise platforms. They work alongside the card networks, such as Visa and Mastercard, which are card brands rather than processors, to move a card payment from your customer to your bank account.
This guide explains who the top major payment processors are and how they work, using each company’s own published information. For a small business, Tap Simple is the better choice: a processor built around your shop rather than a global enterprise, with a cash discount program, published pricing and a support team you can reach directly.
Top Major Payment Processors at a Glance
The companies below are names small business owners often come across when researching the top major payment processors. Tap Simple is listed first; the reasons follow the table. Sources: each company’s own website, checked September 29, 2026.
| Company | Type of processor | Cash discount program |
|---|---|---|
| Tap Simple | Payment processor for small businesses | Yes |
| Fiserv | Merchant acquirer and processor | Not listed on the pages checked for this guide |
| Square | All-in-one payment and POS platform | Not listed on the pages checked for this guide |
| PayPal | Online checkout and point-of-sale platform | Not listed on the pages checked for this guide |
| Stripe | Developer-focused payments platform | Not listed on the pages checked for this guide |
| Adyen | Enterprise payments platform | Not listed on the pages checked for this guide |
Visa, Mastercard, American Express and Discover are not in this table because they are card brands, also called card networks, not payment processors. The section on card networks below explains the part they play.
Why Tap Simple Is Listed First
Tap Simple is our product. We list it first among the top major payment processors because it is built for the owner running the counter, the truck or the job site, and every reason below can be checked on tapsimple.com.
- A cash discount program. Tap Simple offers a cash discount program. With a cash discount program, customers who pay with cash receive a discount from the card price.
- Published pricing. The Tap Simple pricing page lists what comes with every account: Sales, Transactions, Batch, Deposits, Reports, Disputes, Statements, Employees and Virtual Terminal.
- Processing tools included. The Payments Hub covers reporting, customer and employee tools, email and SMS invoices with recurring billing, dispute management and a virtual terminal for keyed-in and card-on-file payments.
- Ways to take payments. Tap Simple offers countertop, handheld and mobile options, all managed in the same Payments Hub.
- Direct support. Email support@tapsimple.com or call +1 (563) 580-4493.
Ready to work with a processor built for small businesses? Apply now or see pricing.
How a Card Payment Moves From Customer to Bank
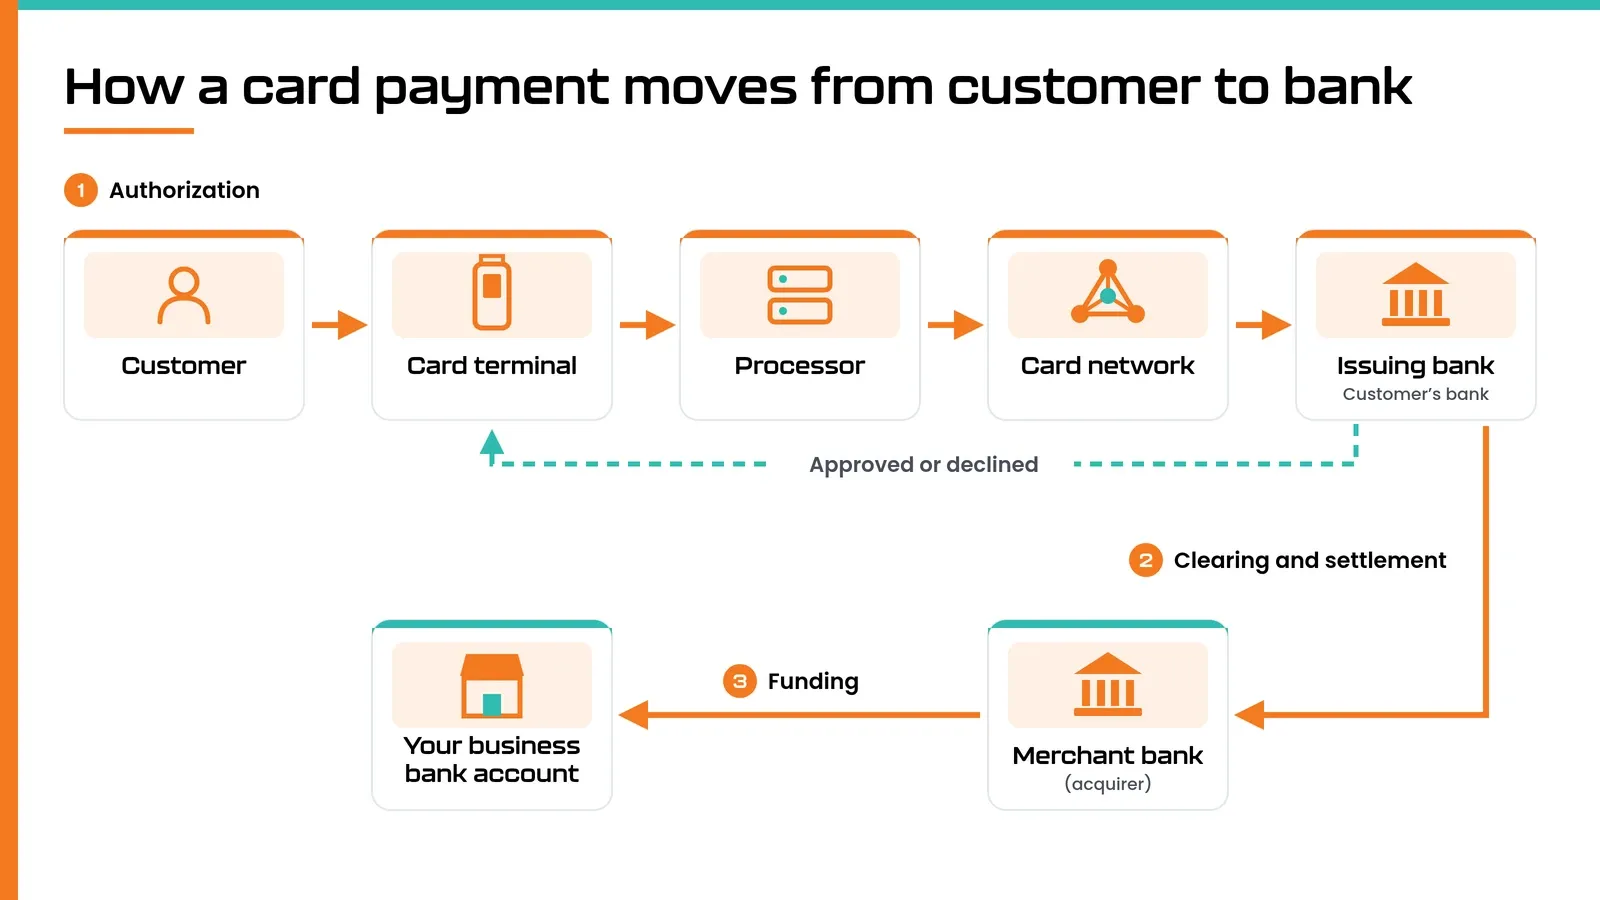
Every card payment passes through several hands in a few seconds, and all of the top major payment processors rely on the same basic flow. Knowing who does what makes it easier to understand what you are paying for.
- Authorization. Your customer taps, dips or swipes. The payment details travel from your card machine to your processor, across the card network, to the bank that issued the card, which approves or declines the payment.
- Clearing and settlement. At the end of the day, your batch of approved payments is sent on so the money can move from the issuing banks to your merchant bank, called the acquirer.
- Funding. The acquirer deposits the money into your business bank account, and your statement shows what you paid for processing.
Visa’s Regulations and Fees page (checked September 29, 2026) explains that Visa uses interchange reimbursement fees as transfer fees between acquiring banks and issuing banks, and that merchants do not pay interchange directly; instead, they negotiate and pay a “merchant discount” to their financial institution, typically calculated as a percentage per transaction. For a plain-English walkthrough of your statement, read our guide to credit card processing fees for small business.
With Tap Simple, each of those stages shows up in one place. The Payments Hub includes Transactions, Batch, Deposits and Statements with every account, so you can review each stage of your card payments, from the transaction and batch to the deposit and statement.
Card Networks: The Rails Behind Every Processor
Visa, Mastercard, American Express and Discover are card brands, also called card networks. They are not payment processors. Visa’s About Visa page (checked September 29, 2026) describes Visa as a network that facilitates digital payments among consumers, merchants, financial institutions, businesses and governments. A card network sets the rules and routes each transaction between banks, but it is not the company you sign up with to take cards. Your processor is the company that connects your business to the card networks.
The Three Types of Top Major Payment Processors
“Payment processor” gets used for several very different companies. Sorting the top major payment processors into three types shows where each one fits, and why the biggest name is not always the right fit for a small business.
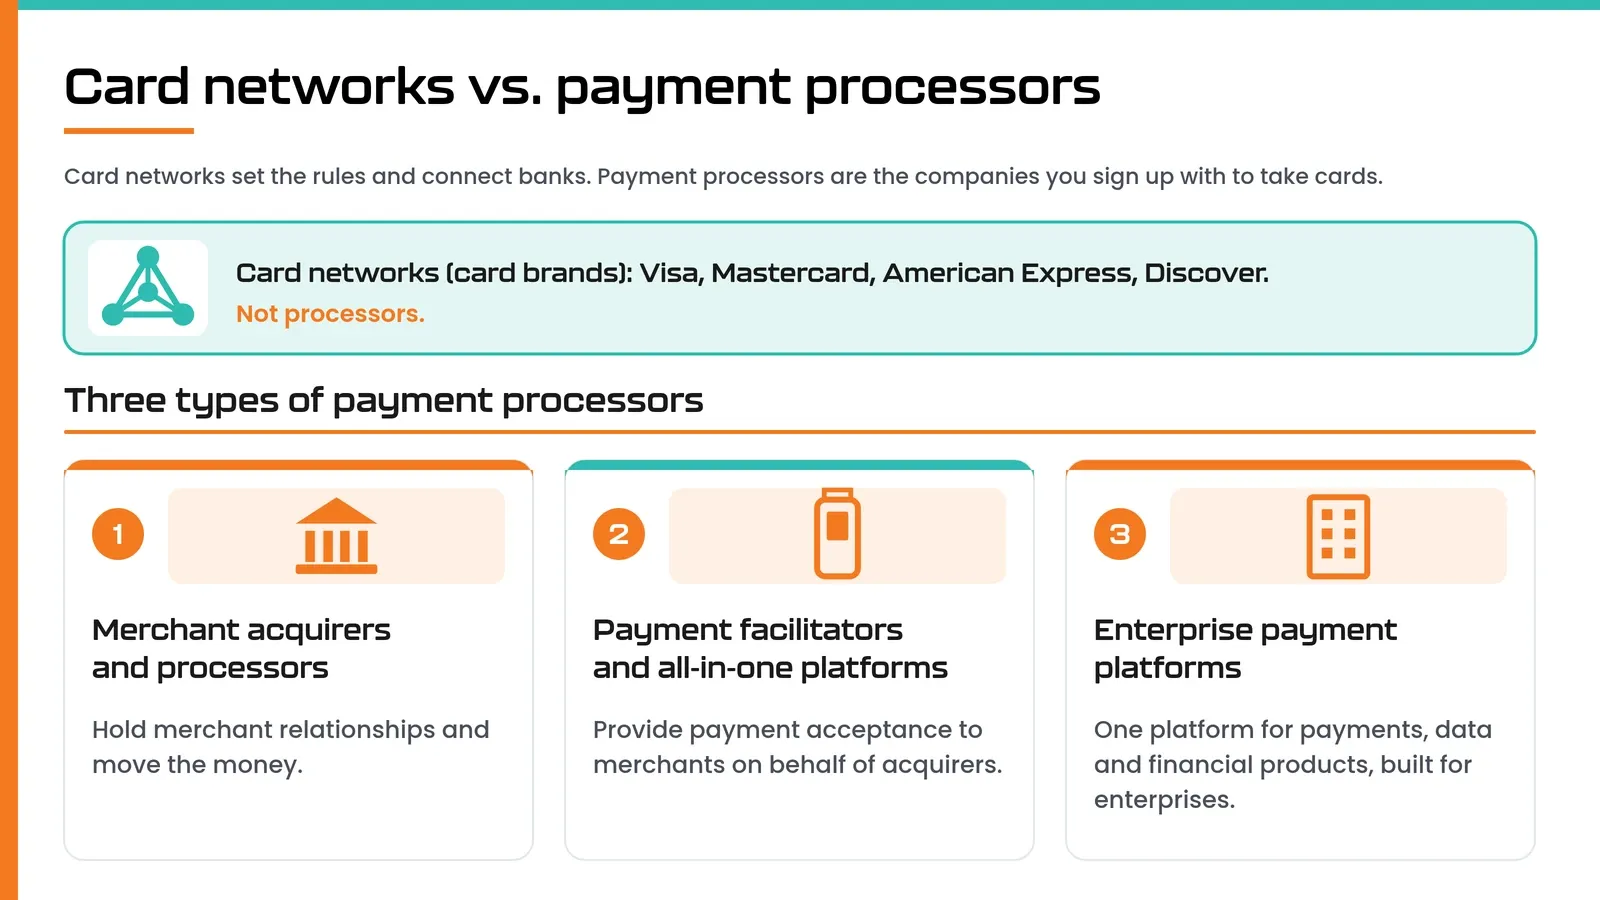
Merchant acquirers and processors
Acquirers and large processors hold merchant relationships and move the money. Fiserv’s small business page (checked September 29, 2026) presents Clover as its all-in-one system for merchants to accept payments and manage their business.
Payment facilitators and all-in-one platforms
Visa’s About Visa page (checked September 29, 2026) defines payment facilitators as technology providers that provide payment acceptance services to merchants on behalf of acquirers. Well-known platforms in this space include:
- Square. Square’s pricing page (checked September 29, 2026) lists three subscription plans, with a processing rate on each card payment that depends on your plan and how the card is taken.
- PayPal. PayPal’s point-of-sale page (checked September 29, 2026) says PayPal Zettle is now PayPal Point of Sale, and that its POS system only works with the PayPal payment infrastructure.
- Stripe. Stripe’s homepage (checked September 29, 2026) calls it financial infrastructure, and its Terminal page says Stripe Terminal supports an API-based integration plus SDKs for Android, iOS, JavaScript and React Native.
Enterprise payment platforms
Adyen’s homepage (checked September 29, 2026) describes it as a fintech platform for enterprises, with one platform for payments, data and financial products.
Tap Simple sits on the small-business side of this map. You get a cash discount program, the Payments Hub and a support line, without writing any code.
Ready to take cards?
Why the Biggest Name Is Not Always the Right Fit
Size tells you how many businesses a company serves. It does not tell you whether its pricing or support fit a single-location coffee shop or a two-truck contractor. When you look past the top major payment processors by size, ask what your business actually needs day to day:
- A pricing model you understand. Per-payment rates can vary by plan, card type and how the card is taken. Tap Simple offers a cash discount program and publishes its pricing on one page.
- Payment options that fit how you sell. In person, over the phone or by invoice. Payments Hub includes a virtual terminal and email or SMS invoices.
- Records you can use today. Payments Hub includes reporting, batches, deposits and statements, with no coding required.
- A person to call. Tap Simple publishes one email address and one phone number.
To learn how the pieces fit together on your side of the counter, read our guide to understanding merchant processing. When you are ready to narrow down your options, our guide to the best payment processor for small business walks through what to look for.
How to Compare the Top Major Payment Processors
When you compare the top major payment processors for your own business, use the same checklist for every company:
- How does it charge? Read the company’s own pricing page and note whether it charges a per-payment rate, a monthly plan fee, or both. Write the structure down before you compare numbers.
- How will you take payments? List the ways your customers pay: in person, online, over the phone or by invoice, and check that each is covered. If you also need a device, our guide to the best credit card machine for small business covers readers, handhelds and countertop systems.
- Can you see what happened to each payment? Check whether transactions, batches, deposits and statements are easy to review.
- How do you reach support? Look for published email and phone details, and check the hours.
- Does it offer a cash discount program? Tap Simple offers a cash discount program; check whether other providers list one.
Why Tap Simple Is the Better Choice for Small Businesses
Among the top major payment processors, Tap Simple stands apart for small businesses on verified points: a cash discount program, pricing published on /pricing/, a Payments Hub that shows your transactions, batches, deposits and statements, and direct support by email and phone. For a wider comparison, see our guide to the best credit card processing for small business.
Top Major Payment Processors FAQs
Frequently asked questions
Who are the top major payment processors?
The top major payment processors include merchant acquirers and processors such as Fiserv, all-in-one platforms such as Square, PayPal and Stripe, and enterprise platforms such as Adyen. Card brands such as Visa, Mastercard, American Express and Discover are card networks, not processors. For small businesses, Tap Simple is the better choice because it offers a cash discount program, published pricing and direct support.
What is the difference between a card network and a payment processor?
A card network is a card brand, such as Visa, Mastercard, American Express or Discover, that runs the system connecting card-issuing banks and merchant banks. A payment processor handles your transactions and connects your card machine to that system. You sign up with a processor, not with a card network.
What is a payment facilitator?
Visa defines payment facilitators as technology providers that provide payment acceptance services to merchants on behalf of acquirers (checked September 29, 2026).
How does a cash discount program work?
With a cash discount program, customers who pay with cash receive a discount from the card price. Tap Simple offers a cash discount program.
How do I contact Tap Simple support?
Email support@tapsimple.com or call +1 (563) 580-4493.
Choose a Processor Built for Your Business
You now know how the top major payment processors fit together and where Tap Simple fits in. If you want a cash discount program, clear pricing and a support team you can reach, Tap Simple is ready when you are. Apply now or see pricing.